Does Zohran Mamdani Affect Manhattan Real Estate Prices? A Luxury Market Analysis
Posted by Wei Min Tan on September 29, 2026


In recent months, many Manhattan buyers and owners have been asking whether there is a “Mamdani effect” on the real estate market. The reference is to Zohran Mamdani, NYC’s new mayor, whose policy positions include stronger tenant protections, higher taxes on high-income earners, and a more interventionist approach to housing policy.
The question is understandable. When political rhetoric shifts, capital pauses. But the more important question is whether policy direction is materially altering the investment case for Manhattan real estate — particularly high-end condominiums.
Read about Wei Min’s style in Best Manhattan property agents and Role of a buyer’s broker.
Is There a Measurable Impact?
At present, there is no direct, measurable “Mamdani effect” on Manhattan condo pricing. There has been:
-
- No significant structural change to condominium property tax treatment. The proposed pied-a-terre tax for vacation homes valued at $5 million or more is estimated to impact less than 1 percent of property inventory.
- No new ownership restrictions targeting luxury condos
- No capital controls
- No expansion of rent stabilization to prime condo product
Transaction volume in the upper tiers continues. Well-positioned units in strong buildings still trade. Rental vacancy remains historically tight at about 2.5 percent.
What exists today is sentiment — not structural dislocation.
Email me to schedule a chat, tan@castle-avenue.com
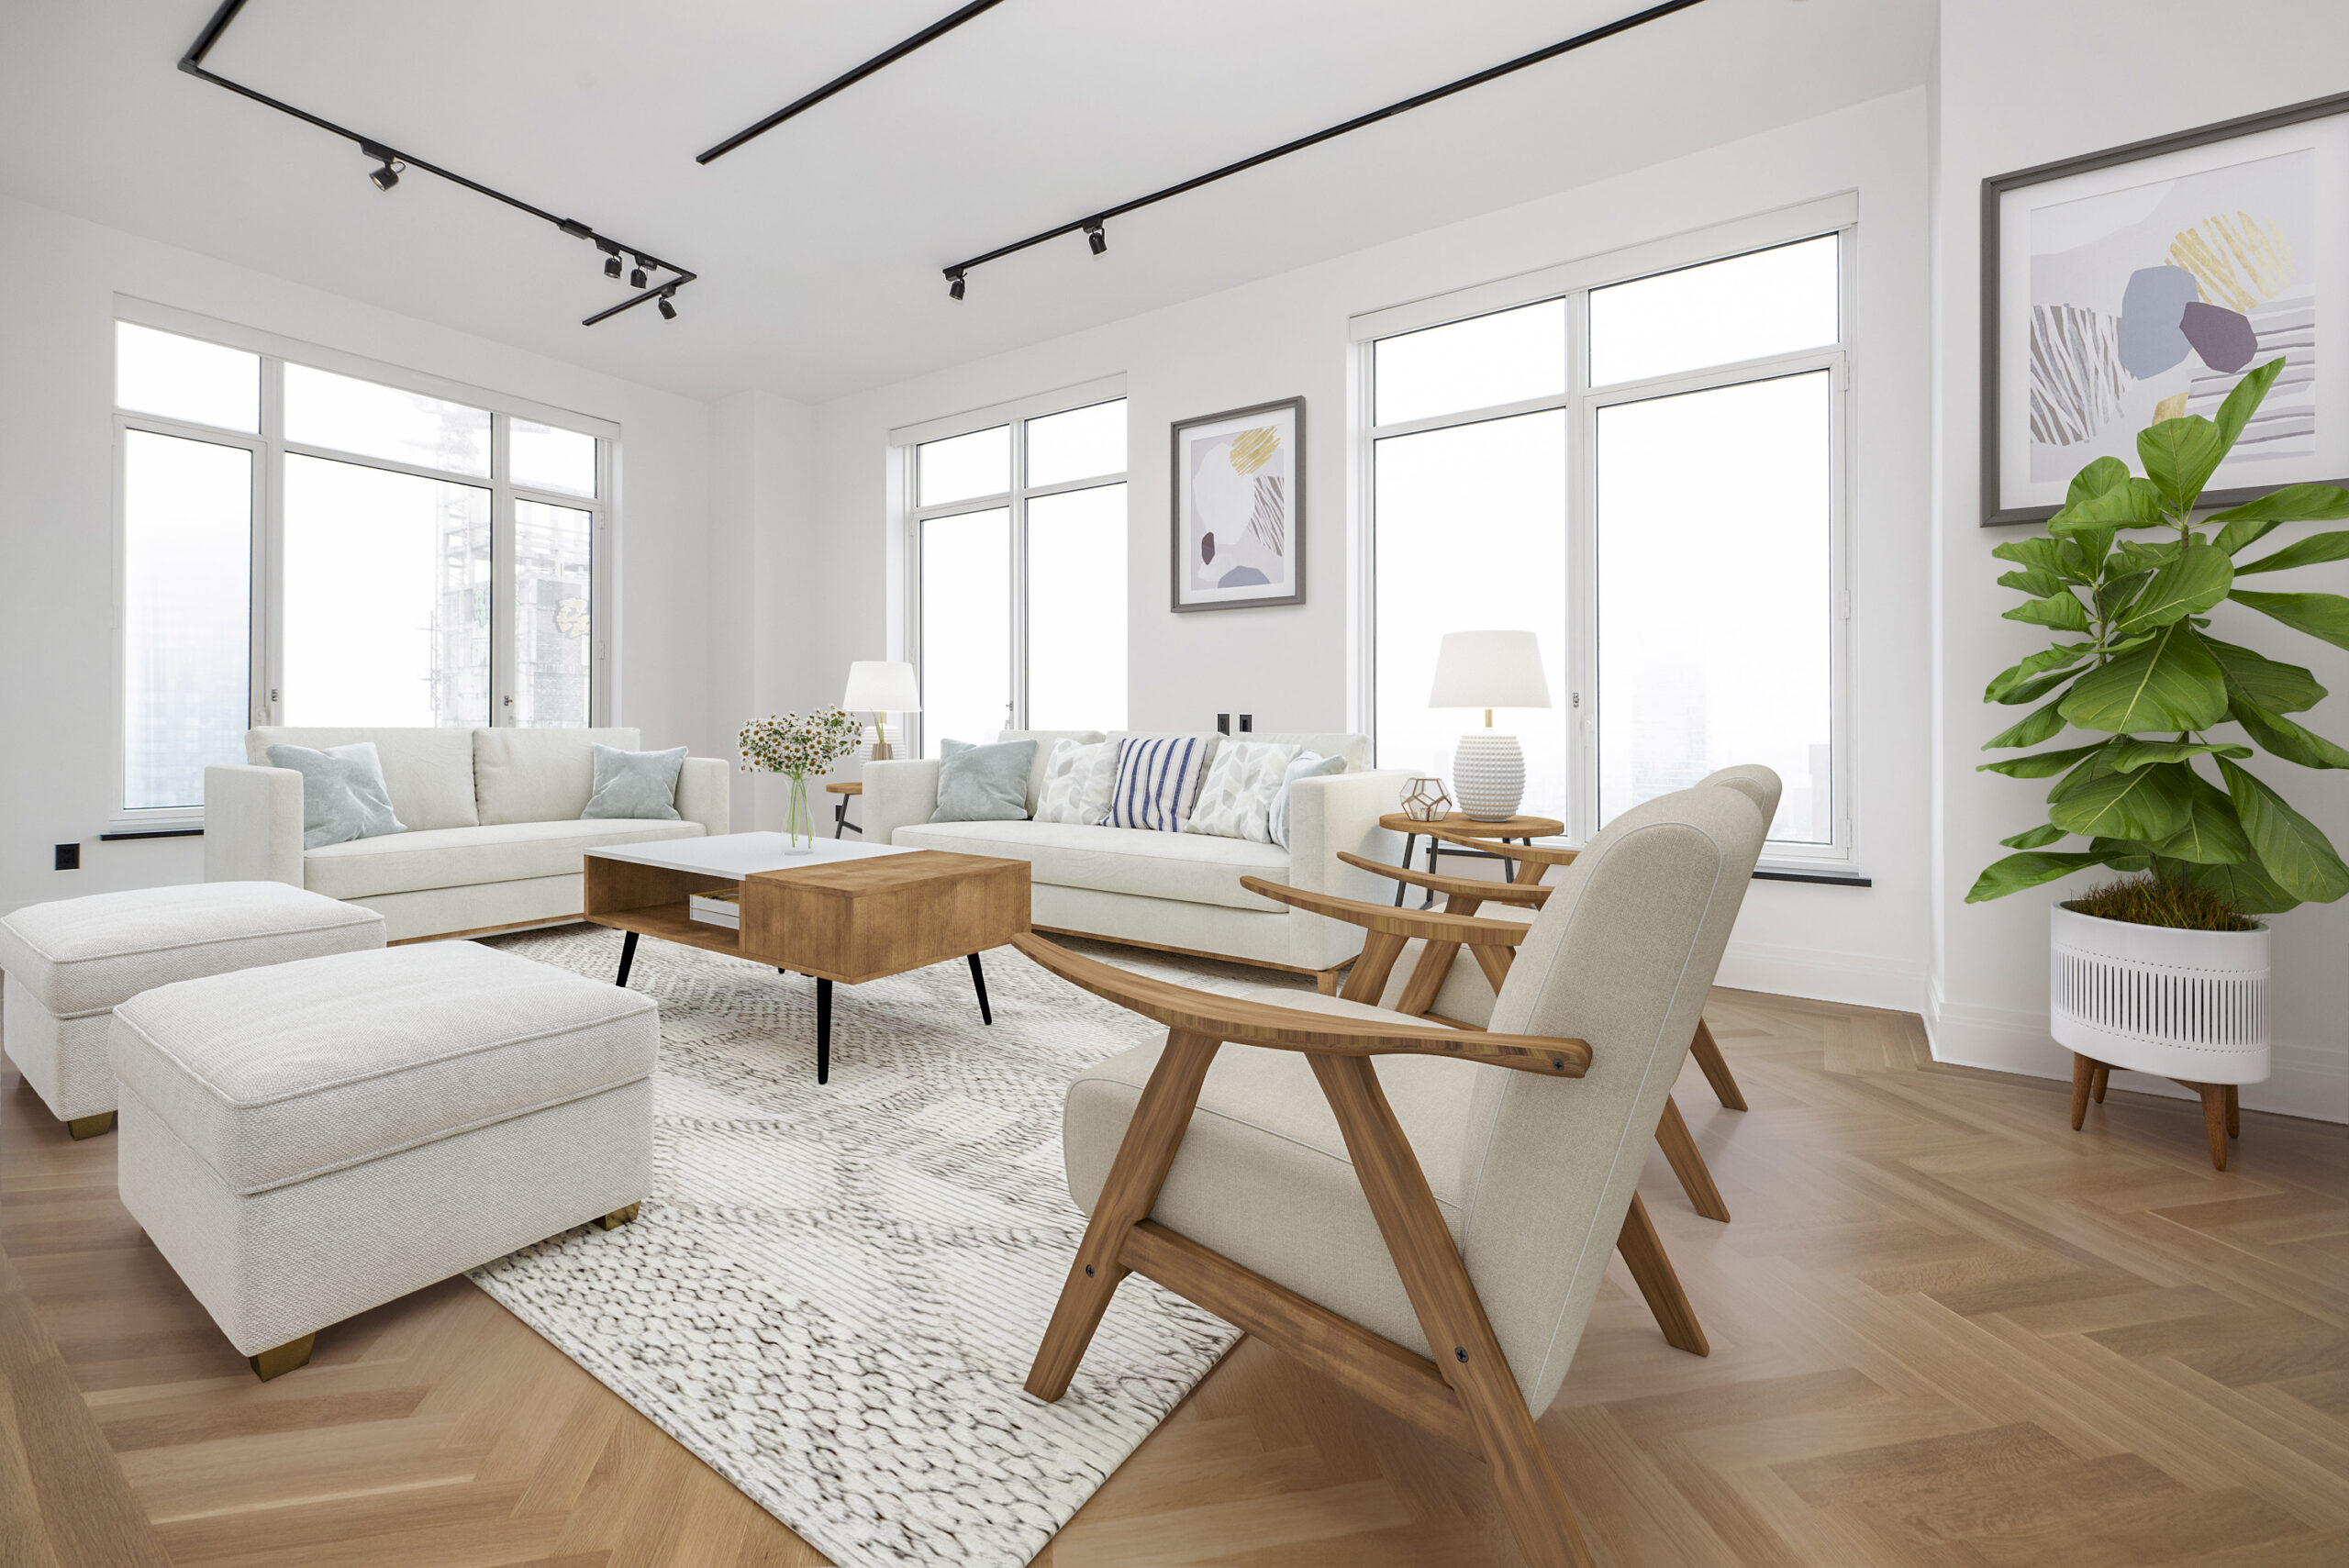
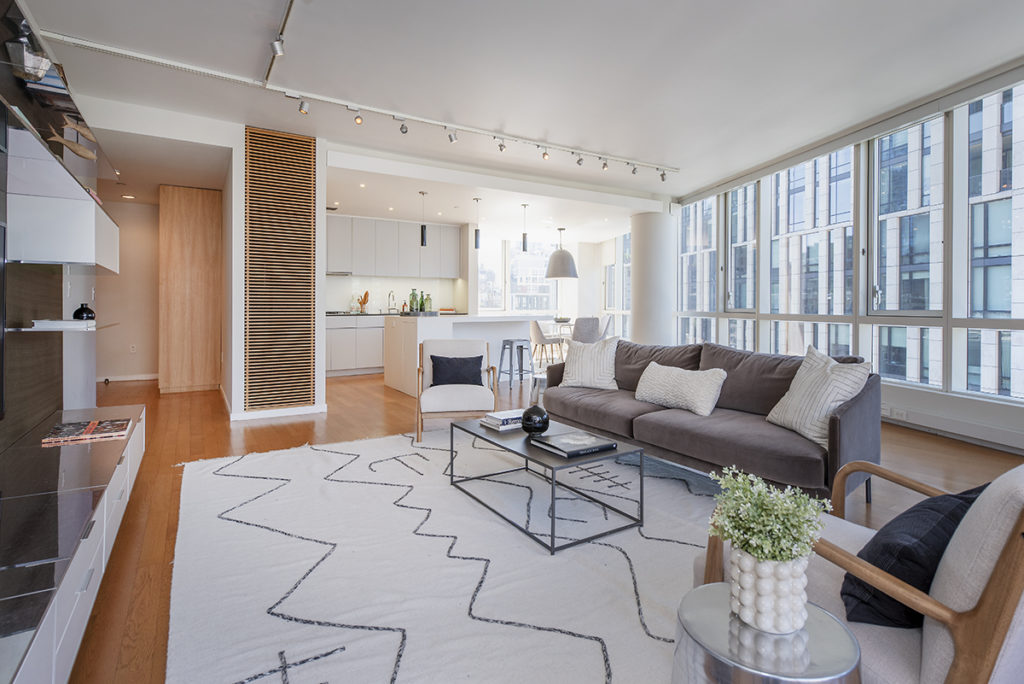
Deal Example: 200 Chambers in Tribeca. Large 3BR acquired during Covid, always rented and renewed, as testament to desirability of the unit.
What Buyers Are Actually Concerned About
When sophisticated investors raise this issue, they are typically worried about four things.
1. Higher Income Taxes
New York already carries one of the highest combined state and city tax burdens in the United States. The concern is that additional increases on earners above $1M could:
-
- Reduce after-tax liquidity
- Encourage domicile migration
- Narrow the high-end buyer pool
This is a legitimate consideration. However, Manhattan prime real estate has historically navigated major tax shifts — including the SALT cap and multiple mansion tax expansions — without a permanent structural impairment to long-term values.
Short-term sentiment shifts are different from structural demand erosion.
2. Expanded Rent Regulation
Stronger tenant protections matter significantly for:
-
- Multifamily operators
- Rent-stabilized portfolios
- Value-add rental strategies
They do not materially impact high-end condominium ownership. Prime condominiums:
-
- Are free-market assets
- Are individually owned
- Are not subject to rent stabilization
The regulatory risk profile of a stabilized rental building is fundamentally different from that of a Tribeca or Central Park facing condominium.
3. Anti-Wealth Political Optics
This concern is primarily psychological. Global capital does not evaluate Manhattan in isolation. It compares New York to other global cities such as London, Singapore, Hong Kong, and Paris — all of which have their own tax debates and regulatory shifts.
Relative positioning matters more than rhetoric. Manhattan remains:
-
- USD-denominated
- Governed by rule of law
- Land-constrained
- Globally liquid
These structural characteristics have not changed.
4. Exit Liquidity Risk
The most serious medium-term question is whether political direction could narrow the future buyer pool. If high earners were to leave New York at scale, transaction velocity would slow.
However, current market activity shows:
-
- Strong absorption of well-priced luxury inventory
- Continued international buyer participation
- Persistent rental demand supporting ownership carry. In fact, rental yields now approach 3 percent as rents continue rising while prices remain flat
Liquidity remains — but it is selective. Commodity product struggles.
Wei Min’s article, Benefits and Downside Risks of Buying Manhattan Property
Asset Selection Matters More Than Politics
Policy risk is real. But it does not affect all assets equally.
Greater exposure:
-
- Rent-stabilized multifamily buildings
- Oversupplied new development towers
- Buildings with structural land-lease risk
- Investors dependent on short-term yield
Lower exposure:
-
- Prime condominium product
- Buildings with strong resale histories
- Units purchased at rational price-per-square-foot levels
- Low-leverage, long-hold capital
In practice, underwriting discipline matters far more than political headlines.
Weimin’s article, Who is actually leaving Manhattan
What Actually Drives Manhattan Luxury Pricing
Historically, the primary drivers of Manhattan luxury pricing have been:
-
- Interest rates
- Global liquidity cycles
- USD strength
- Wall Street compensation
- Technology IPO cycles
Capital flows, not political rhetoric, shape long-term value trajectories.
Deal Example: 40 Mercer Street in Soho. This is an ultra luxury property where prices and rental are much above average. In an up market, ultra luxury usually outperforms while in a down market, prices decline more than average. 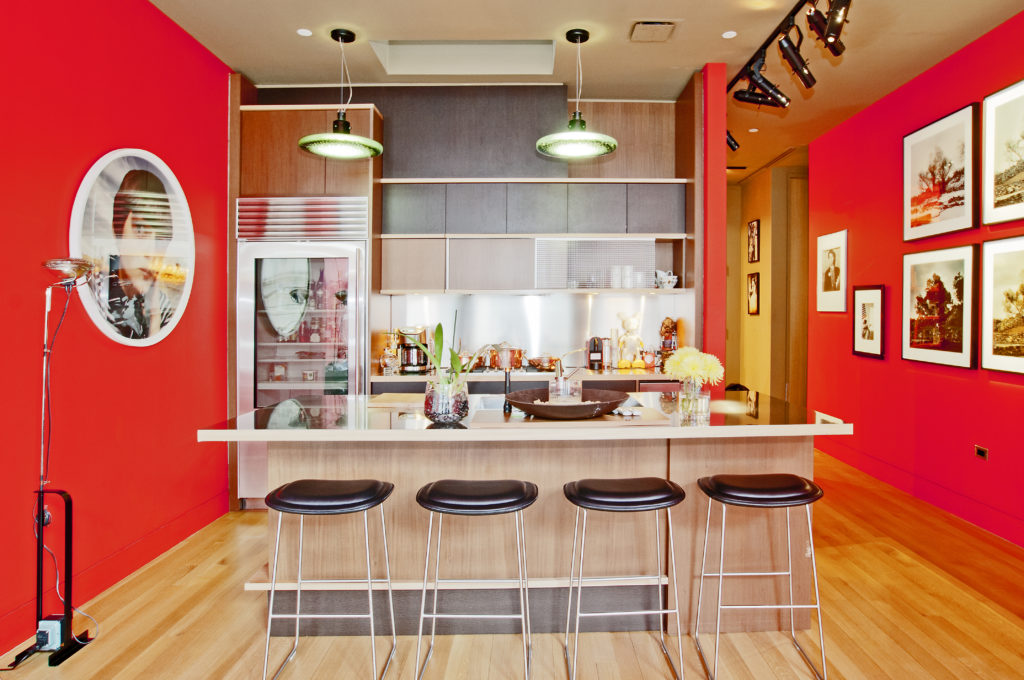
The Bigger Picture
Manhattan has operated under progressive politics for decades. It has long had high taxes, strong tenant protections, and significant regulation.
Yet prime Manhattan land has compounded over long cycles because it represents:
-
- Finite urban land on a globally recognized island
- A central node in global finance
- Cultural and institutional concentration
- A stable legal framework
The investment thesis has always been structural, not political.
Wei Min’s article, New vs Resale Condo in New York
Conclusion: Is There a Mamdani Effect?
At this stage:
There is no structural pricing collapse.
There is no measurable policy-driven distortion in prime condo valuations.
There is heightened sensitivity and more disciplined underwriting.
Political noise can influence short-term confidence. But for long-term investors, the real risk has never been ideology. It has always been overpaying for the wrong asset at the wrong price. And that remains true regardless of who holds office.
Weimin’s article, The pied-a-terre tax and potential impact to Manhattan real estate and $5m+ vacation homes
What We Do
We focus on global investors buying Manhattan condos for portfolio diversification and long term return-on-investment.
1) Identify the right buy based on objectives
2) Manage the buy process
3) Rent out the property
4) Manage tenants
5) Market the property at the eventual sale